
The Costly Reset: What It Means for Homeowners
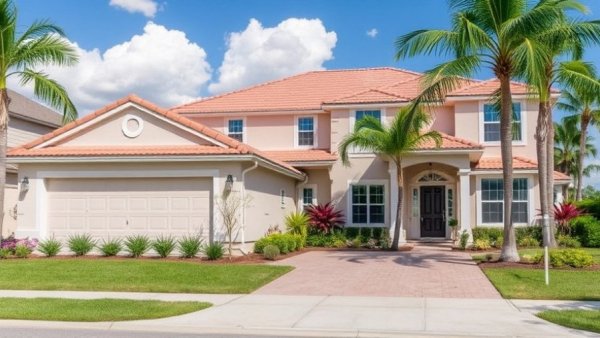
As we approach 2027, a looming financial headache threatens tens of thousands of American homeowners. Approximately 74,000 individuals with seven-year adjustable-rate mortgages (ARMs) could see their monthly payments soar by a staggering median of $1,066, an increase of 36%. This situation stems from a sharp rise in interest rates as their introductory loan periods come to an end, marking a monumental shift from the historically low rates secured during the pandemic.
The Impending Interest Rate Surge
Financial experts project that the interest rate on these loans, which initially hovered around 2.75%, will jump to an estimated 5.79% after the first reset. Such dramatic increases may not only trigger immediate budgetary crises for many families but also set off a ripple effect across the housing market as borrowers struggle to adapt.
These increases are particularly jarring considering that the initial phase of these loans provided homeowners with affordable rates, enabling home purchases during an economically uncertain time. Now, however, borrowers face a stark contrast between their past payments and the new costs they will soon incur. As ICE reports, the total population of ARMs resetting in 2027 could reach around 180,000, showing that this is not merely a niche issue affecting a few homeowners.
Refinancing: A Complicated Solution
For many, the natural inclination might be to refinance into a conventional fixed-rate mortgage. However, the current borrowing environment complicates this course of action. As of mid-November 2026, Freddie Mac noted that the average fixed mortgage rate stood at 7.11%, which is even higher than the rates to which ARMs are adjusting. The irony here is palpable: refinancing would mean exchanging an adjustable-rate mortgage for a higher fixed-rate loan—essentially locking in a worse deal, all while trying to escape the surging interest costs that come with ARMs.
An Unpredictable Future: Potential Consequences
The ramifications of these mortgage resets extend beyond individual homeowners. Nationally, a wider shift in financial behavior may occur, as borrowers begin to shy away from ARMs entirely due to past affordability and changing market conditions. The increased payment obligations will likely exacerbate financial strain for many households already stretched to their limits by rising living costs post-pandemic.
If current index levels remain constant, homeowners with these loans could see rates rise as high as 6.34%, leading to potential monthly payment increases well over $1,200. Such scenarios not only threaten individual finances but could also dampen consumer confidence in the housing market.
Understanding the Broader Market Context
Despite the challenges ahead, it is important to contextualize ARMs within the larger U.S. housing finance landscape. Currently, ARMs make up only about 5.6% of the 3.1 million active first-lien mortgages. While that sounds small, the ramifications of their resets will impact a segment of homeowners significantly—especially those who may struggle with limited financial literacy or guidance.
Moreover, the recent uptick in ARM mortgage locks signifies that there is still interest in adjustable-rate products, likely driven by rising fixed rates. Understanding how these instruments function and their associated risks will become increasingly vital as borrowers weigh their options.
Final Thoughts: Preparing for the Shift
As we near 2027, it’s critical for homeowners impacted by ARMs to start strategizing now to navigate the imminent changes. Engaging with mortgage professionals, educating oneself about financial products, and exploring personalized financial planning can help mitigate the impending effects of pending resets.
While each homeowner’s situation is unique, proactive measures can offer stability in a time of uncertainty, ensuring individuals and families are prepared to handle the financial shifts ahead.


Write A Comment